
Major stock exchange’s crisis extends beyond uncertainty over ZiG: Analysts
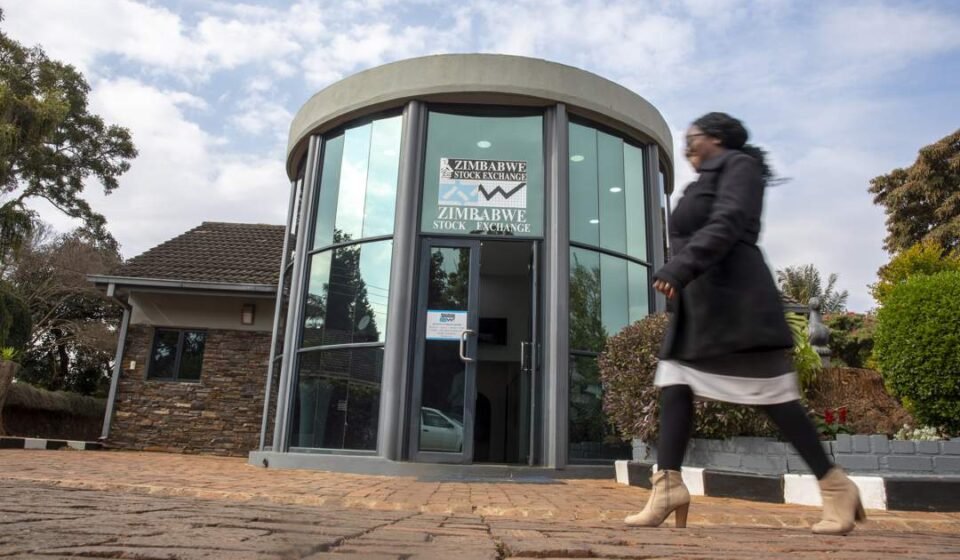
Capital market analysts this week called for an overhaul of Zimbabwe’s financial markets. A growing number of companies are abandoning the Zimbabwe Stock Exchange (ZSE) or plan to leave. That raises questions about the future of the country’s oldest bourse.
Analysts say the crisis facing the Zimbabwe Gold (ZiG)-indexed ZSE goes beyond currency uncertainty. They want the bourse to open to US dollar trading and win back investor confidence.
Tanganda joins the exodus
Agro-industrial group Tanganda Tea Company announced last week that it plans to delist from the century-old ZSE. The bourse has already lost several blue-chip companies to the Victoria Falls Stock Exchange (VFEX). That alternative exchange launched only six years ago, and its US dollar trading platform makes it more attractive.
Tanganda’s move brings to 10 the number of companies that have left, announced plans to leave or seek to migrate to VFEX. The others are Econet Wireless Zimbabwe, which has already delisted, TSL Limited, First Mutual Properties, Old Mutual, Dairibord Holdings, Ariston Holdings, Unifreight Africa, Cottco Holdings and troubled retailer OK Zimbabwe.
Four ZSE counters delisted in 2025. They were Khayah Cement, Truworths, Old Mutual ZSE Top Ten ETF and National Tyre Services.
The exodus has raised concerns about the ZSE’s ability to provide credible valuations and raise capital. It also threatens investor confidence amid persistent liquidity constraints and currency distortions.
Justin Bgoni, chief executive officer at ZSE Holdings, which also controls VFEX, told the Zimbabwe Independent this week that the traditional bourse remains relevant.
Analysts blame liquidity and price discovery
Financial analyst Sylvester Mupanduki said liquidity shortages, poor price discovery and currency distortions weigh on the ZSE. The exchange previously ranked among Africa’s best bourses.
“These were the reasons cited in shareholder circulars by nine of the 15 companies that have delisted since 2020,” Mupanduki said.
“This points to a problem that extends beyond currency denomination to the exchange’s ability to provide credible price discovery, sufficient liquidity and an effective platform for capital raising.”
He cautioned against treating the migration to VFEX as an automatic solution.
“The experience of National Foods, Edars and African Sun, which migrated to the VFEX before subsequently delisting, suggests that changing the currency denomination of an exchange does not, on its own, resolve underlying market-efficiency challenges,” Mupanduki said.
He called for further research to establish whether migration has improved investor returns and company performance. He also warned that regulatory inaction could accelerate the erosion of market depth and investor confidence.
A currency story before an exchange story
Iain Banda, corporate finance analyst at Fincent Securities, said a currency mismatch drives the migration. Companies generate value in one currency, but the market values them in another.
“The migration is best understood as a currency story before it is an exchange story,” Banda said.
He explained that Zimbabwe’s corporate sector has substantially dollarised. Many businesses earn most of their revenue, pay operating costs, service debt and pay dividends in US dollars. Meanwhile, the ZSE still prices and settles trades in ZiG.
“When a company earning over 90% of its revenue in US dollars is valued in a thin local-currency market with an official rate that diverges from the parallel rate, the share price stops being a reliable signal of the business,” he said.
Banda said this weakens companies’ ability to use shares to raise capital, finance acquisitions and offer shareholders an exit. Restricted foreign investor access, thin trading and the low cost of moving to VFEX also speed up the shift.
Market capitalisation concentrates in a few counters
The impact shows in how market capitalisation splits between the two exchanges. Banda said Econet made up roughly a third of the ZSE’s market capitalisation when it left. Its exit contributed to a nearly 24% drop in the exchange’s capitalisation in April.
Delta Corporation, the beverages manufacturer, now accounts for an estimated 46% of ZSE market capitalisation. That shows how heavily the bourse depends on a handful of counters.
Big departures also threaten liquidity in smaller counters. They leave fewer natural buyers, wider bid-ask spreads and more erratic price movements.
“The remaining ZSE-listed companies are therefore not simply losing peers; they are losing the market infrastructure, liquidity and investor attention that gave their listing value in the first place,” Banda said.
He estimated VFEX’s market capitalisation at about US$3.6 billion. That is well ahead of the ZSE’s US$2.9 billion, or US$3.3 billion, depending on the exchange rate applied.
More migrations are coming
Pressure on the ZSE is unlikely to ease soon. TSL completed its migration in July, and Old Mutual Limited Zimbabwe began trading on VFEX in August. Ariston Holdings’ board approved a proposed migration in September. Dairibord Holdings and Unifreight Africa remain at cautionary or regulatory-process stages.
FBC Securities sees a rebalancing, not a collapse
FBC Securities, in its third-quarter economic and capital markets report, described the developments as a gradual rebalancing. It does not see a wholesale shift away from the ZSE.
The brokerage expects VFEX to attract exporters and other foreign currency earners. The ZSE, it said, would keep an important role in mobilising domestic savings and facilitating investment by pension funds and other local institutions.
FBC Securities cautioned that migration alone will not guarantee liquidity. Sustainable trading on both platforms depends on transparent regulation, consistent disclosures, efficient custody and settlement systems, and sufficient free float.
Calls for one multicurrency market
Banda said Zimbabwe needs to rethink the structure of its capital markets. He proposed either introducing US dollar trading on the ZSE or merging the two exchanges under ZSE Holdings into a single multicurrency market.
“The country does not need two exchanges competing for the same issuers; it needs one credible, liquid, multi-currency market,” he said.
The Bankers Association of Zimbabwe also called for greater policy clarity. In its submission to the Ministry of Finance for the 2027 National Budget, it urged government to clarify the roles of the ZSE, VFEX and the Victoria Falls International Financial Services Centre.
The association also asked for targeted tax incentives, rather than additional taxes. These would encourage investment in priority value chains such as agro-processing and manufacturing.
FBC Securities maintained that the two exchanges can complement each other. VFEX can support US dollar capital formation, while the ZSE stays important for domestic equity investment and local-currency savings.
ZSE Holdings responds
Responding to the Independent’s inquiries, Bgoni said: “There remains a role for a local-currency capital market.”
“However, tight ZiG liquidity, currency risk and limited trading are real challenges, particularly when much of the economy’s business and savings are in US dollars. We have relaxed entry requirements and are working to simplify investor access, improve company information, support investor education and develop a stronger pipeline of issuers and investment products,” he said.
Bgoni added: “These efforts need greater institutional participation and supportive currency and investment policies. Lower costs and simpler processes help, but companies also need investors willing and able to provide capital. Departures reduce the ZSE’s listing base and investor choice. The effects on market capitalisation and liquidity depend on the size of the company and whether its shares traded actively. Capital does not automatically move into the remaining counters.
“Migrations to VFEX retain companies within Zimbabwe’s public capital markets, but do not resolve the ZSE’s liquidity challenges. Our response is to improve access, costs and the range of investment opportunities while engaging government and regulators on the underlying policy constraints. Investor confidence ultimately depends on credible companies and the ability to buy and sell regularly at fair prices.”
Reporting based on original coverage by Zimbabwe Independent.